Oracle (NYSE: ORCL) — Q1 FY2027 Post Earnings

Oracle ORCL q1 27 post earnings Finance Note

Operations

Q1 2027
Q1 Revenue ↑ 29.6% YoY $19.35B
Segments
Cloud and Software 88.7%
Hardware 4.0%
Services 7.3%

Key Earnings Driver

Cloud Infrastructure Cloud and Software revenue increased 32.9% year over year, with Cloud revenue increasing 61.5% to $11.6B, while Software revenue declined 3% to $5.5B. Within Cloud, Cloud Applications revenue increased 9.9% to $4.2B and Cloud Infrastructure revenue increased 120.7% to $7.4B. Hardware revenue increased 15.5% to $0.8B, and Services revenue increased 4.8% to $1.4B. Oracle’s Q1 total revenue increase reflected strong execution in its Cloud Infrastructure business, with the delivery of 850MW additional datacenter capacity.

Key Operating Metrics¹

METRIC

STATUS

Cloud and Software↑ 32.9%

Cloud↑ 61.5%

Cloud Infrastructure↑ 120.7%

🟢 Scaling

Cloud Applications↑ 9.9%

Software↓ 3.0%

Software License↓ 14.5%

🟡 Watch

Software Support↓ 1.2%

🟡 Watch

Key Financial Metrics

Gross Margin 60.03% -4.7 pp YoY
Backlog / Revenue 3,431.9% 34.31x Qtr Rev
CapEx Intensity 147.32% 1.47x Revenue

Key Operating Metrics¹: Core operating metrics relevant to revenue, sourced from website and/or SEC filings for Q, with status based on reported data.
Oracle (NYSE: ORCL) — Q1 FY2027 Pre Earnings

Pre earnings note company quarterly analysis

Operations

Q4 2026
Q4 Revenue ↑ 20.6% YoY $19.18B
Segments
Cloud and Software 87.3%
Hardware 4.8%
Services 7.9%

Key Earnings Driver

Multicloud AI Database Cloud and Software revenue increased 22.1% year over year, with Cloud revenue increasing 47.1% to $9.9B, while Software declined 2.1% to $6.8B. Within Cloud, Cloud Infrastructure revenue increased 93.2% to $5.8B, with management reporting that Multicloud AI Database increased 404% and was its fastest-growing business ever, and Cloud Applications revenue increased 10.3% to $4.1B. Hardware increased 8.7% to $0.9B, and Services increased 13.0% to $1.5B.

Key Operating Metrics¹

METRIC

STATUS

Cloud and Software↑ 22.1%

Cloud↑ 47.1%

Cloud Infrastructure↑ 93.3%

Multicloud AI Database↑ 404.0%

🟢 Scaling

Cloud Applications↑ 10.2%

Software↓ 2.1%

Software License↓ 6.3%

🟡 Watch

Software Support↓ 0.4%

🟡 Watch

Key Operating Metrics¹: Core operating metrics relevant to revenue, sourced from website and/or SEC filings for Q, with status based on reported data.
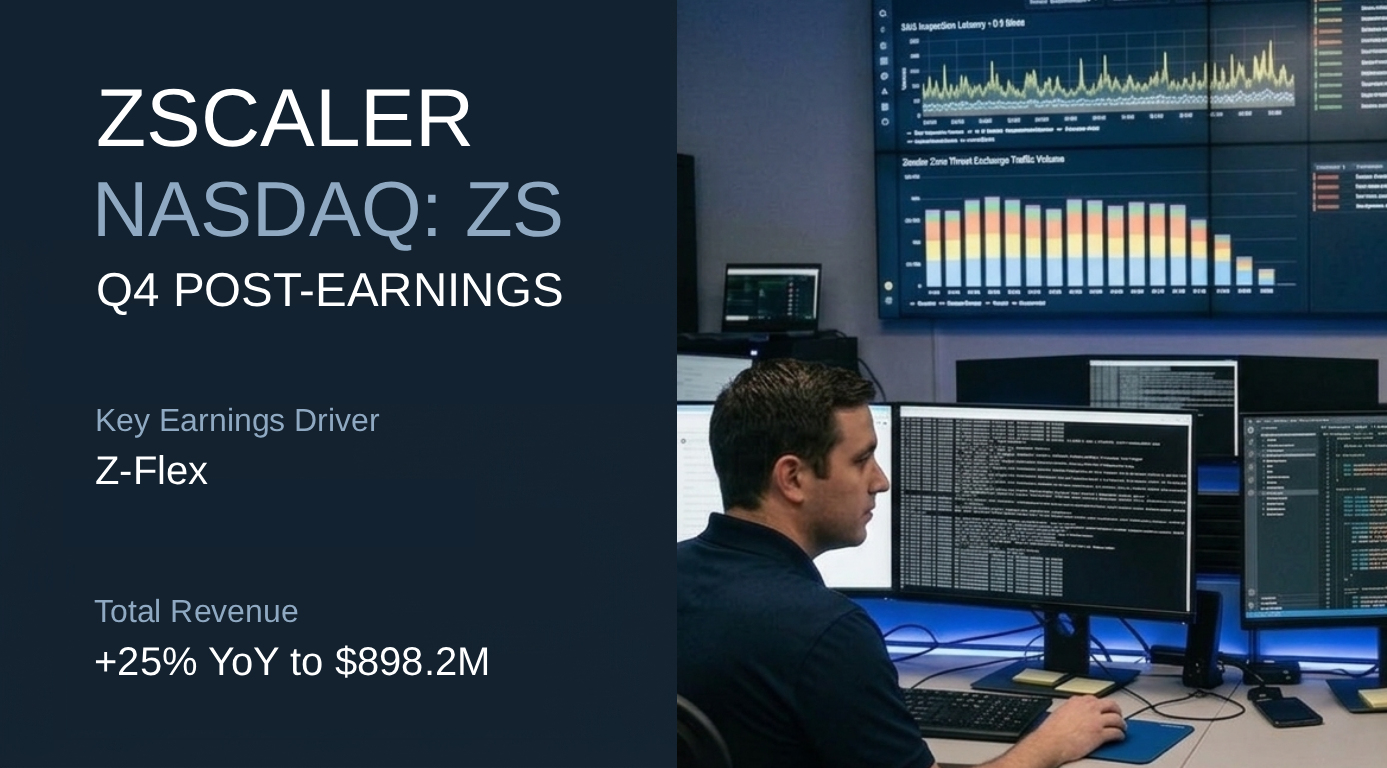
Zscaler (NASDAQ: ZS) — Q4 FY2026 Post Earnings

Zscaler ZS q4 post earnings finance note

Operations

Q4 2026
Q4 Revenue ↑ 24.9% YoY $898.2M
Segments
Zscaler 100.0%

Key Earnings Driver

Z-Flex Zscaler revenue increased 24.9% year over year to $898.2M. Within Zscaler, Z-Flex TCV exceeded $770M in Q4, increasing more than 60% quarter over quarter, and exceeded $1.7B for FY2026. Management cited increasing contribution from non-seat-based solutions and continued Z-Flex momentum.

Key Operating Metrics¹

METRIC

STATUS

Zscaler↑ 24.9%

Z-Flex

🟢 Scaling

Key Financial Metrics

Gross Margin 77.00% +1 pp YoY
Backlog / Revenue 819.8% 8.19x Qtr Rev
CapEx Intensity 22.25% 0.22x Revenue

Key Operating Metrics¹: Core operating metrics relevant to revenue, sourced from website and/or SEC filings for Q, with status based on reported data.
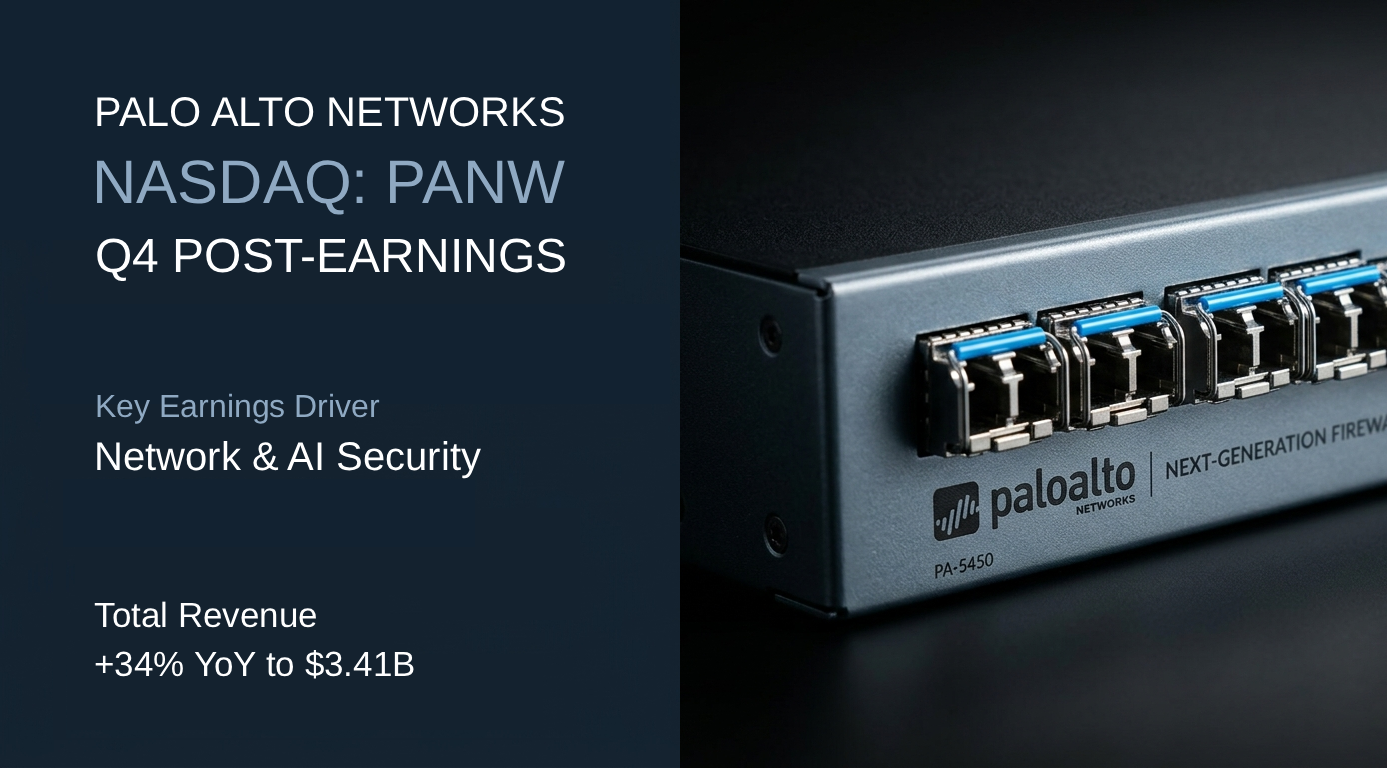
Palo Alto Networks (NASDAQ: PANW) — Q4 FY2026 Post Earnings

Palo Alto Networks panw q4 26 Post Earnings

Operations

Q4 2026
Q4 Revenue ↑ 34.5% YoY $3.41B
Segments
Network & AI Security 68.4%
Cortex 17.2%
Idira 9.8%
Other 4.6%

Key Earnings Driver

Cortex Network & AI Security revenue increased 17% year over year to $2.3B. Cortex revenue increased 25% to $586M. Idira revenue increased 21% pro forma to $336M. Other revenue increased 5% to $157M. Network & AI Security represented 68% of revenue and was the largest reported platform. Management attributed the quarter’s strength to Network & AI Security, Cortex, and Idira.

Key Operating Metrics¹

METRIC

STATUS

Network & AI Security↑ 17.0%

Cortex↑ 25.0%

🟢 Scaling

Key Financial Metrics

Gross Margin 74.80% -1 pp YoY
Backlog / Revenue 621.7% 6.21x Qtr Rev
CapEx Intensity 3.02% 0.03x Revenue

Key Operating Metrics¹: Core operating metrics relevant to revenue, sourced from website and/or SEC filings for Q, with status based on reported data.

CrowdStrike Holdings, Inc. (NASDAQ: CRWD) — Q2 FY2027 Post Earnings

Operations

Q2 2027
Q2 Revenue ↑ 25.8% YoY $1.47B
Segments
Subscription 95.2%
Professional Services 4.8%

Key Earnings Driver

Falcon Platform Subscription revenue increased 27% year over year to $1.4B and Professional Services revenue increased 7% to $70.6M. Module adoption rates for Subscription customers using six or more Falcon modules reached 51%.

Key Operating Metrics¹

METRIC

STATUS

Subscription↑ 27.0%

Falcon Platform

🟢 Scaling

Key Financial Metrics

Gross Margin 75.00% +1 pp YoY
Backlog / Revenue 401.0% 4.01x Qtr Rev
CapEx Intensity 10.26% 0.10x Revenue

Key Operating Metrics¹: Core operating metrics relevant to revenue, sourced from website and/or SEC filings for Q, with status based on reported data.

CrowdStrike Holdings, Inc. (NASDAQ: CRWD) — Q2 FY2027 Pre Earnings

Pre earnings note company quarterly analysis

Operations

Q1 2027
Q1 Revenue ↑ 25.6% YoY $1.39B
Segments
Subscription 95.3%
Professional Services 4.7%

Key Earnings Driver

Falcon Platform Subscription revenue increased 25.7% year over year to $1.32 billion. Subscription revenue growth was primarily driven by new customer additions and sales of additional sensors and modules to existing customers. 51% of CrowdStrike’s subscription customers were using six or more Falcon modules. Professional Services revenue increased 23.0% to $64.8M.

Key Operating Metrics¹

METRIC

STATUS

Subscription↑ 25.7%

Falcon Platform

🟢 Scaling

Key Financial Metrics

Gross Margin 75.00% +1 pp YoY
Backlog / Revenue 288.7% 2.88x Qtr Rev
CapEx Intensity 8.67% 0.08x Revenue

Key Operating Metrics¹: Core operating metrics relevant to revenue, sourced from website and/or SEC filings for Q, with status based on reported data.

Kingsoft Cloud (NASDAQ: KC) — Q2 2026 Post Earnings

Post earnings note company quarterly analysis

Operations

Q2 2026
Q2 Revenue ↑ 30.8% YoY $3.07B
Segments
Public Cloud Services 76.7%
Enterprise Cloud Services 23.3%

Key Earnings Driver

AI Cloud Services Public cloud services revenue increased 45.1% year over year to RMB2.358 billion. Enterprise cloud services revenue declined 1.3% to RMB714.3 million. Management said the revenue increase was mainly driven by growing demand for AI cloud services

Key Operating Metrics¹

METRIC

STATUS

Public Cloud Services↑ 45.1%

AI cloud services

🟢 Scaling

Enterprise Cloud Services↓ 1.3%

🟡 Watch

Key Financial Metrics

Gross Margin 15.17% +0.75 pp YoY
Backlog / Revenue N/A
CapEx Intensity N/A

Key Operating Metrics¹: Core operating metrics relevant to revenue, sourced from website and/or SEC filings for Q, with status based on reported data.

Kingsoft Cloud (NASDAQ: KC) — Q2 2026 Pre Earnings

Pre earnings note company quarterly analysis

Operations

Q1 2026
Q1 Revenue ↑ 37.3% YoY ¥2.70B
Segments
Public Cloud Services 73.8%
Enterprise Cloud Services 26.2%

Key Earnings Driver

AI Business Public Cloud Services revenue increased 47.5% year over year to RMB1.9963B, with AI Business gross billing increasing 90% and accounting for more than half of Public Cloud Services revenue for the first time. Enterprise Cloud Services revenue increased 14.7% to RMB707.4M, but declined 17.6% sequentially, mainly due to the Chinese New Year impact and differentiated delivery schedules for various projects.

Key Operating Metrics¹

METRIC

STATUS

Public Cloud Services↑ 47.5%

AI Business

🟢 Scaling

Enterprise Cloud Services↑ 14.7%

Key Operating Metrics¹: Core operating metrics relevant to revenue, sourced from website and/or SEC filings for Q, with status based on reported data.